The payment instructions name your supplier’s bank, but the transfer receipt mentions another institution. That extra name can belong to an intermediary bank: a bank helping the sending and receiving institutions complete a payment when their direct arrangements do not cover the route.
It is useful to separate the instruction from the settlement. The FFIEC’s explanation of funds transfers describes how correspondent relationships support the movement of money. A messaging network carries instructions; it is not itself the account into which your supplier receives the funds.
Follow the roles, not just the names
Imagine a small business sending an invoice payment in a currency its customer’s bank does not directly settle with the destination bank. Another institution may provide the connecting relationship. That does not automatically mean the payment is faulty, unusually risky, or destined to be slow. Nor does every international transfer need the same number of banks.
For the customer, the practical question is whether the instructions supplied by the receiving bank require a particular intermediary. Copying an intermediary from an old invoice or a different currency’s instructions can introduce a mismatch. Confirm details through a known contact route, especially when someone emails a last-minute change.
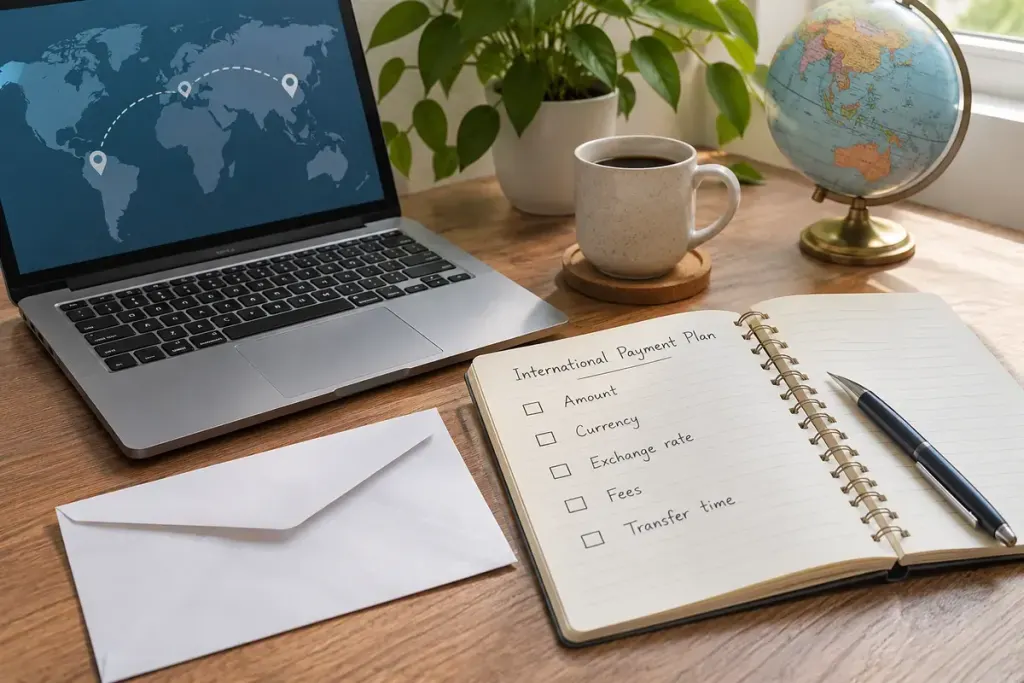
Keep the amount question separate
- Ask what the sender pays in fees and what the recipient is expected to receive.
- Check whether the quoted exchange rate and any intermediary deductions are included.
- Keep the original payment instructions, receipt and invoice together.
If the recipient receives less than expected, ask the sending bank to identify the deduction and the charging arrangement applied. The name of an intermediary alone does not establish who charged what. A useful query includes the amount sent, currency, date and amount received, rather than simply saying that money is missing.
Before sending a second payment to cover a shortfall, establish the first payment’s position. A clear explanation of the route and charges is more useful than guessing from the bank names on a receipt.