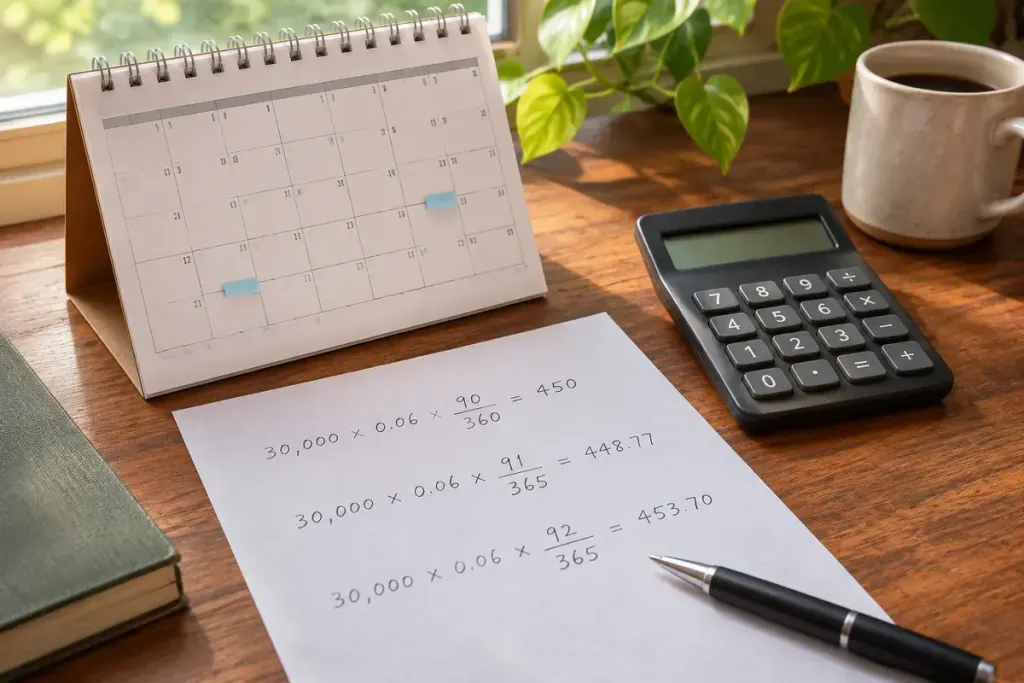
Two interest figures can differ even when the principal and annual rate match. Before looking for a rounding error, check how the calculation turns a period of time into a fraction of a year. That small piece of the contract is the day-count convention.
Separate the calendar from the calculation
An actual-day convention counts the elapsed days in the relevant period. A 30/360 convention instead uses a defined calculation based on thirty-day months and a 360-day year, including rules for particular month-end dates. It does not claim that the calendar has changed.
The MSRB’s Rule G-33 provides a concrete example of a 30/360 calculation in the US municipal-securities market. Its requirements belong to that context; they should not be applied automatically to every savings account, loan or bond.
A small worked example
Imagine a hypothetical simple-interest balance of 10,000 currency units at an annual rate of 6%, with exactly 30 actual days in the period. Ignore fees, tax and compounding for this illustration.
- Using Actual/365 Fixed: 10,000 × 0.06 × 30 ÷ 365 = approximately 49.32.
- Using Actual/360: 10,000 × 0.06 × 30 ÷ 360 = 50.00.
The balance, rate and actual elapsed days are identical. The denominator alone changes the result. Treasury Systems’ convention reference distinguishes these bases and also explains why Actual/Actual and the several 30/360 variants need more precise labels.
Notice that this example does not compare the complete cost of two financial products. Payment timing, compounding, charges and the applicable rate disclosure can matter much more than this single component.
What to request when a figure will not reconcile
Ask for the opening and closing dates, the principal used, the rate, the day-count basis and the treatment of the first and last day. Put those inputs beside the statement rather than trying several denominators until one seems close.
For a changing balance, check whether the provider divides the period into segments. A perfectly correct convention applied to the wrong balance still produces the wrong answer. The useful result is a calculation you can reproduce from the agreed terms, not a familiar-looking percentage.